Financial Planning
Running a small business requires more than offering quality products or services. Business owners must also understand how to manage money, control expenses, plan investments, and prepare for unexpected financial challenges. Without proper financial planning, even a profitable business can struggle to maintain stability and achieve long-term growth.
Financial planning for small businesses helps owners make smarter financial decisions, manage cash flow, and build a strong foundation for the future. It does not always require complicated software or professional financial knowledge. With the right strategies, small businesses can improve their financial management and create opportunities for sustainable success.
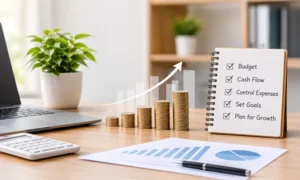
1. Create a Realistic Business Budget
A business budget is one of the most important tools for managing finances. It provides a clear picture of how much money comes into the business and how much goes out.
Small business owners should prepare a monthly budget that includes rent, employee salaries, marketing expenses, inventory, utilities, and other operating costs. They should also estimate expected revenue based on previous sales and current market conditions.
A realistic budget helps businesses avoid unnecessary spending and ensures that money is available for essential activities. Reviewing the budget regularly also makes it easier to identify financial problems before they become serious.
2. Monitor Cash Flow Regularly
Cash flow is the movement of money into and out of a business. It plays a major role in daily operations because businesses need available cash to pay suppliers, employees, rent, and other expenses.
Sometimes, a business may generate good sales but still experience financial difficulties because customers delay payments.
To improve cash flow management, small businesses should track incoming and outgoing payments, send invoices on time, and follow up on overdue accounts. Maintaining sufficient cash reserves can also help cover expenses during slower business periods.
3. Separate Personal and Business Finances
Mixing personal and business money can create confusion and make financial management difficult. It becomes harder to understand actual business profits, track expenses, and prepare accurate financial reports.
Opening a separate business bank account is a simple but effective solution. Business owners should use it for company-related transactions and maintain clear records of personal withdrawals.
This approach improves financial transparency and makes accounting, budgeting, and tax preparation much easier.
4. Set Clear Financial Goals
Every small business should have financial goals that provide direction for future decisions. These goals may include increasing monthly revenue, reducing operating costs, improving profit margins, or expanding into new markets.
Instead of setting general targets, business owners should establish specific and measurable objectives.
For example, a company may aim to increase annual revenue by 15% or reduce unnecessary expenses by 10%. Clear financial goals help business owners measure progress and understand whether their current strategies are delivering results.
5. Control Unnecessary Business Expenses
Managing expenses is essential for maintaining profitability. Small businesses often spend money on subscriptions, equipment, marketing activities, and services that may not provide enough value.
Business owners should review their expenses regularly and identify areas where costs can be reduced without affecting product quality or customer satisfaction.
Comparing supplier prices, negotiating better deals, using affordable digital tools, and avoiding unnecessary purchases can improve financial efficiency.
The goal should not simply be to spend less but to spend money more wisely.
6. Build an Emergency Fund
Unexpected expenses can affect any business. Equipment breakdowns, delayed customer payments, seasonal sales declines, and sudden market changes can create financial pressure.
An emergency fund provides financial protection during difficult periods. Small businesses should gradually set aside a portion of their profits to build a reserve.
Ideally, businesses should work towards maintaining enough savings to cover several months of essential operating expenses. Having this financial backup reduces dependence on emergency loans and allows owners to make decisions with greater confidence.
7. Use Accounting Software and Digital Tools
Managing financial records manually can become time-consuming as a business grows. Accounting software helps simplify bookkeeping, invoice management, expense tracking, and financial reporting.
Small businesses can explore tools such as Zoho Books, QuickBooks, and other accounting platforms that suit their requirements and budgets.
These tools reduce manual work and provide better visibility into financial performance. Regularly updated records also help business owners understand profitability and identify areas that need improvement.
8. Plan for Taxes and Financial Obligations
Tax planning should be an important part of every small business’s financial strategy. Ignoring tax obligations can lead to penalties, unnecessary stress, and unexpected financial difficulties.
Business owners should maintain proper invoices, organize expense records, understand applicable tax requirements, and set aside money for upcoming payments.
For businesses operating in India, understanding GST requirements, income tax obligations, and other applicable regulations is particularly important. Consulting a qualified accountant can help ensure compliance and prevent costly mistakes.
9. Review Financial Performance Every Month
Financial planning is not something businesses should do only once a year. Regular reviews help owners understand whether their business is moving in the right direction.
Important financial indicators include revenue, operating expenses, net profit, cash flow, outstanding payments, and debt levels.
Comparing monthly results with previous periods can reveal useful patterns. If expenses are increasing faster than revenue, business owners can take corrective action before profitability suffers.
Conclusion
Improving financial planning is essential for small businesses that want to achieve stability, profitability, and long-term growth. By creating realistic budgets, monitoring cash flow, controlling expenses, setting financial goals, and maintaining emergency savings, business owners can manage their resources more effectively. Using digital accounting tools and reviewing financial performance regularly can further strengthen financial decision-making. Good financial planning is not just about managing today’s money; it is about preparing the business for tomorrow’s opportunities and challenges. With consistent effort and smart financial decisions, small businesses can build a more secure and successful future.